
Your credit score can play an important role in your financial life. Whether you are applying for a credit card, personal loan, auto loan, or mortgage, your credit history may be one of the factors lenders consider when evaluating your application. A good credit score can demonstrate a history of responsible credit management and may help you qualify for more favorable borrowing terms.
But what is a good credit score, and what can you do if your score is lower than you would like? Understanding your personal credit score, the different categories within the credit score range, and the habits that influence your score can help you make more informed financial decisions.
Improving your credit does not usually happen overnight. However, consistent habits such as making payments on time, managing balances responsibly, and monitoring your credit information can help you work toward a stronger credit profile.
What Is a Credit Score?
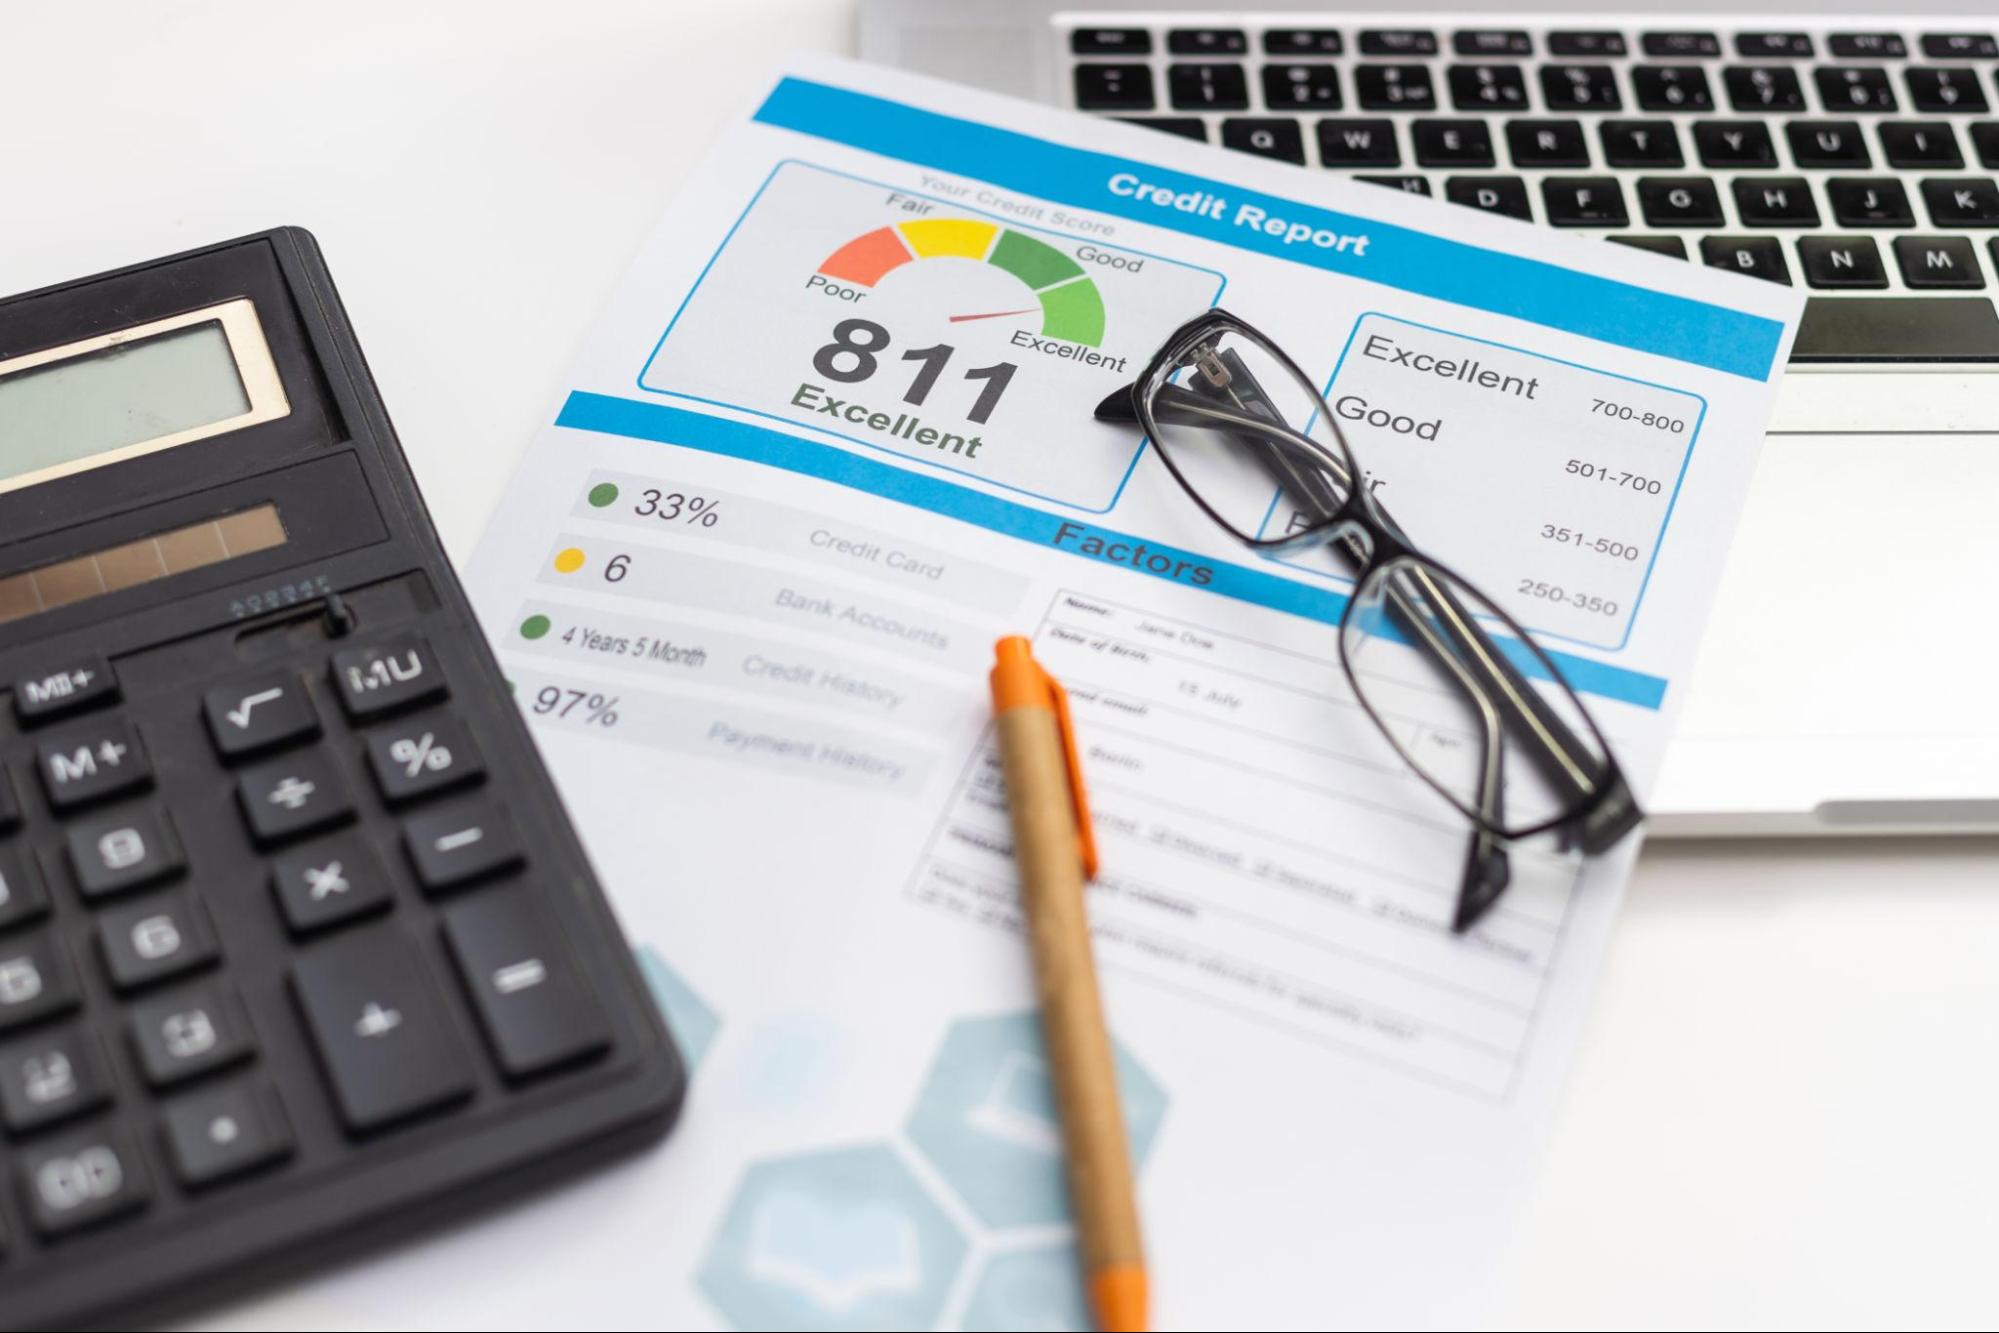
A credit score is a numerical representation of information in your credit report. It is designed to help lenders assess the potential risk associated with extending credit. Credit scoring models can consider information such as your payment history, amounts owed, length of credit history, new credit, and credit mix.
FICO Scores, one widely used scoring system, generally range from 300 to 850. The higher the score, the lower the credit risk generally appears to lenders. However, a credit score is only one part of a lending decision. Lenders may also consider factors such as income, existing debt, employment, the type of credit requested, and other information.
Understanding your personal credit score is therefore useful, but it is equally important to understand what information is contributing to it.
What Is Considered a Good Credit Score?
If you are wondering what is considered a good credit score, FICO generally considers a score of 670 to 739 to be good. Scores from 740 to 799 are considered very good, while scores of 800 or higher are considered exceptional.
Here is a general breakdown of the FICO credit score range:
| Credit Score Range | General Rating |
|---|---|
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Exceptional |
A score does not guarantee approval for a particular financial product. Different lenders may use different scoring models and have their own requirements. Still, knowing where your score falls within the range can give you a useful starting point for understanding your credit profile.
Why Does a Good Credit Score Matter?
A good credit score can be valuable when you are looking to borrow money. Lenders generally use credit information to help evaluate the likelihood that a borrower will repay their obligations as agreed.
A stronger credit profile may make it easier to qualify for certain financial products and can potentially help you receive more favorable terms. However, the exact impact of your score depends on the lender, loan type, your overall financial profile, and other factors.
For example, someone preparing to purchase a home may want to understand their credit position before exploring mortgage and home loan options. Similarly, someone considering other borrowing options can review CTB Connect’s borrowing solutions to better understand the types of credit available.
What Credit Score Do You Need for a Loan?
There is no single answer to what credit score do you need for a loan. Different lenders and loan products can have different eligibility requirements, and approval decisions are generally based on more than just your credit score.
For example, a lender may also evaluate your income, debt obligations, payment history, credit report, loan amount, and other financial information. Some loans may be available to borrowers with fair credit, while stronger credit may improve the range of options or terms available.
Instead of focusing only on reaching a specific number, consider building a healthy overall credit profile. Understanding your credit and reviewing your borrowing options before applying can help you make more informed decisions.
What Factors Affect Your Personal Credit Score?
Your personal credit score is influenced by information contained in your credit report. For FICO Scores, the information is grouped into five major categories: payment history, amounts owed, length of credit history, new credit, and credit mix.
Payment history is the largest category, accounting for 35% of a FICO Score. Amounts owed accounts for 30%, while length of credit history accounts for 15%. New credit and credit mix each account for 10%. These percentages are general guidelines, and the importance of individual factors can vary depending on a person’s credit profile.
| Credit Factor | General FICO Weight | What It Represents |
|---|---|---|
| Payment History | 35% | Whether you have paid credit obligations on time |
| Amounts Owed | 30% | How much debt and available revolving credit you are using |
| Length of Credit History | 15% | How long your credit accounts have been established |
| New Credit | 10% | Recent applications and newly opened credit |
| Credit Mix | 10% | The variety of credit accounts in your profile |
This is why improving credit is not about focusing on one action alone. Several aspects of your credit behavior work together to influence your score.
How to Improve Your Credit Score
If you are asking how to improve credit score, start with the habits that have the greatest potential impact. Making payments on time is particularly important because payment history is the largest FICO scoring category.
Managing the amount of revolving credit you use is another important consideration. A high credit utilization ratio can negatively affect your score, while lower utilization can be more favorable.
Reviewing your credit reports can also help you identify information that may need attention. If you find inaccurate information, follow the appropriate process for disputing it with the relevant credit reporting agency.
You should also be cautious about applying for multiple new credit accounts in a short period. New credit applications can result in inquiries, and opening several accounts quickly can affect different parts of your credit profile.
How to Improve Your Credit Score Fast
The phrase “how to improve your credit score fast” can make it sound as though there is a quick fix. In reality, there is no guaranteed shortcut that works for every credit profile.
If your score is being affected by high revolving balances, reducing those balances may help. If late payments are affecting your credit history, getting current and maintaining on-time payments can help establish a stronger pattern over time. However, the effect and timing will vary depending on your individual credit report.
Avoid companies or strategies that promise an instant or guaranteed score increase. Sustainable credit improvement generally comes from responsible financial behavior maintained over time.
How to Build Credit
For someone with limited or no credit history, learning how to build credit can be an important part of establishing financial independence.
The goal is to demonstrate that you can responsibly manage credit. This means using credit carefully, making payments on time, and avoiding taking on more debt than you can comfortably manage.
Building credit is not about borrowing as much as possible. Instead, responsible use and consistency are more important. Over time, positive credit information can help establish a stronger credit history.
If you are looking for additional financial education, CTB Connect’s financial resources and CTBeacon provide educational content covering different personal finance topics.
How to Get a Good Credit Score
If you want to know how to get a good credit score, focus on building habits rather than chasing a particular number. Start by understanding your current credit position and identifying the areas that need the most attention.
For example, if payment history is the main issue, prioritize paying every account on time. If high balances are affecting your profile, create a realistic strategy for reducing them. If your credit history is relatively new, maintaining accounts responsibly over time can help establish a longer history.
Your approach should also fit your overall financial situation. Credit improvement works best when it is part of a broader personal finance strategy that includes budgeting, saving, and responsible borrowing.
Common Credit Mistakes to Avoid
Even small financial habits can affect your credit profile over time. Avoiding common mistakes can help you maintain progress toward a good credit score.
- Missing or making late payments on credit accounts.
- Applying for several new credit accounts within a short period.
- Using a large portion of your available revolving credit.
- Ignoring your credit reports and potential inaccuracies.
- Taking on debt that does not fit comfortably within your budget.
The objective is not to avoid credit completely. Responsible credit use can help you establish a positive history, while excessive or poorly managed borrowing can make your financial situation more difficult.
Simple Habits That Can Help Maintain Good Credit
Once you have worked toward a stronger credit profile, maintaining it is just as important as improving it. Good credit management should become part of your regular financial routine.
- Pay your credit obligations on time.
- Keep revolving balances manageable.
- Monitor your credit information regularly.
- Apply for new credit only when it makes financial sense.
- Review your overall budget before taking on additional debt.
Creating a realistic budget can make it easier to ensure that credit payments fit within your monthly finances. CTB Connect also provides banking solutions that can support everyday financial management.
How Long Does It Take to Improve Your Credit Score?
One of the most common questions is how long does it take to improve your credit score? There is no fixed timeline because the answer depends on what is affecting your score and what changes are made.
Some changes can be reflected relatively quickly after new information is reported, while rebuilding a history affected by serious negative information can take much longer. FICO notes that credit scores evolve as information in credit reports changes.
The best approach is to focus on actions you can control. Pay accounts on time, manage balances responsibly, avoid unnecessary applications, and give positive credit behavior time to build.